For decades, the jewelry store has organized much of its business around a fairly predictable calendar. Engagements, weddings, anniversaries, birthdays, Christmas or Valentine’s Day provided brands with regular consumption occasions and, with them, arguments to activate campaigns, launch collections and generate traffic to stores.
But that scheme is losing rigidity. Purchasing jewelry for oneself gains weight and expands the circumstances in which the consumer considers it appropriate to purchase a piece. The change has a particularly relevant reading from marketing: a category traditionally associated with gifts is increasing its consumption occasions without the need to create new functionalities for the product.
“The State of Fashion 2026”, prepared by McKinsey & Company and The Business of Fashion, precisely places self-gifting among the factors that are driving the good performance of jewelry compared to other fashion categories. 42% of women and 35% of men surveyed say they buy more jewelry for themselves than they did two or three years ago. The report also points out that the category will grow in units at a faster rate than other areas of fashion.
The data reveals a change greater than the simple increase in purchases. It means incorporating occasions into the market that previously had less presence and reducing dependence on large traditional milestones.
Social occasions give way to personal motivations
A wedding or an anniversary are socially defined events and, therefore, relatively easy to codify through communication. The self-gift introduces a much broader map of motivations: from a birthday to a professional promotion, a trip, a personal achievement or a spontaneous purchase.
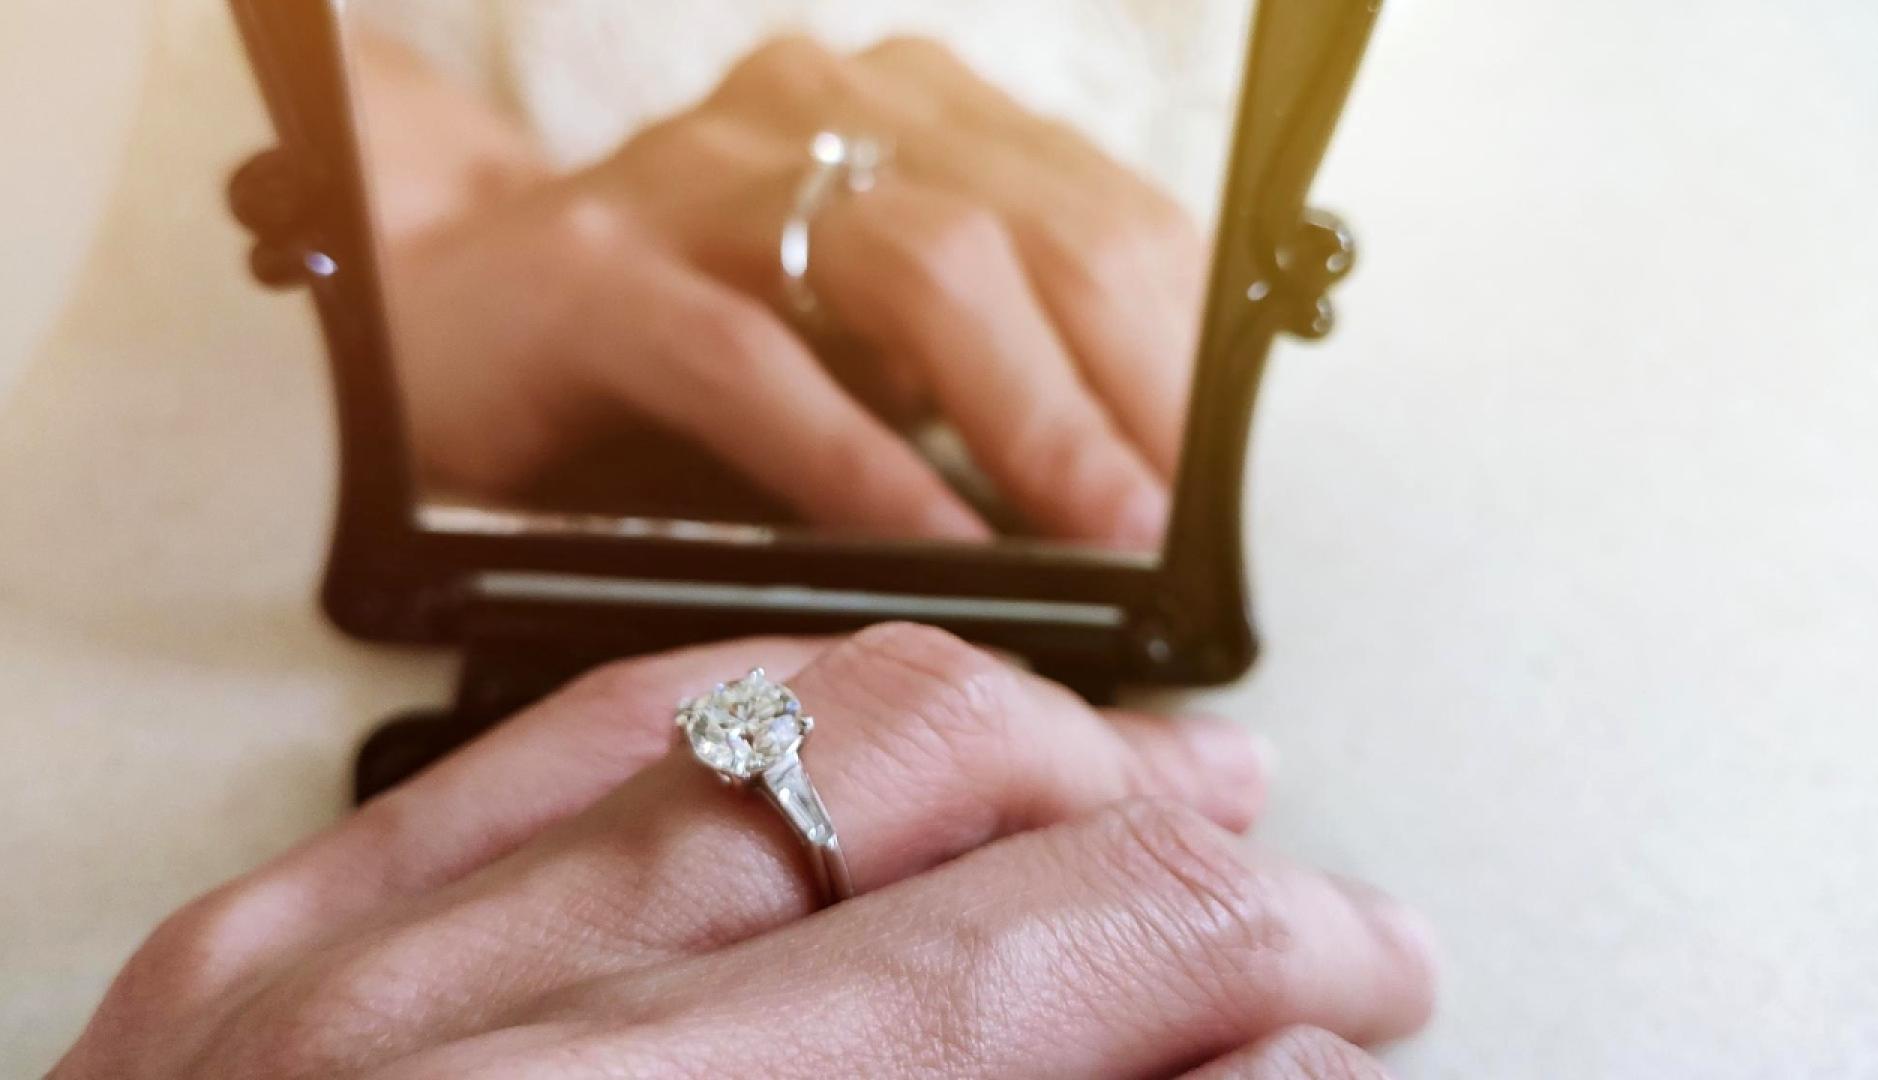
Rings are already the jewel that is most frequently purchased for oneself.
The “Jewelry Self-Purchaser Study” research, published by Jewelers Mutual in 2026, identifies birthdays, holidays and shopping as a specific occasion among the main triggers for purchasing jewelry for oneself. It also shows differences in motivations: men have a greater tendency to link these purchases with achievements and milestones, while among women spontaneous purchases are more present. Rings, in addition, now appear as the type of jewelry that study participants most frequently acquire for themselves, ahead of necklaces and earrings.
For brands, the consequence is important. The more reasons the consumer finds to enter a category, the greater the number of moments in which that category can be relevant. And this is affecting even products historically linked to very specific codes. The solitaire ring is a good example of this. Its association with commitment continues to be the majority, although it currently shares space with other purchase motivations. Anyone considering buying a solitaire ring can choose it to mark a relationship and also as a piece linked to their style, an achievement or a personal purchasing decision.
The offering of the brands themselves reflects this diversification. In the case of Tous, the category incorporates different designs, materials, sizes and price ranges, with options in gold and platinum and proposals with natural and laboratory-created diamonds. The variety allows a historically highly codified typology to find a fit for different profiles, budgets and motivations.
Expand the market by expanding the codes
The evolution is especially interesting from a marketing perspective because it demonstrates that the growth of a category does not depend solely on attracting new consumers. It can also come from increasing its potential frequency and broadening the contexts in which the product makes sense.
The diamond market offers a reference to this evolution. According to the “US Diamond Acquisition Study” by De Beers, carried out on 18,500 American women between 18 and 74 years old, occasions not linked to weddings or engagements already represent 75% of the value of the demand for natural diamonds in the United States. Purchasing for oneself reaches 31% and, in this sense, the company also identifies new jobs, promotions, personal achievements and purchases made without a specific event among the motivations that are gaining more strength.
The data corresponds to the US market and cannot be transferred directly to the Spanish consumer, but it allows us to observe how an industry strongly built around commitment is finding growth outside that traditional territory.
McKinsey notes that jewelry is becoming more associated with personal expression versus the occasion
The role of identity also changes. McKinsey notes that jewelry is becoming increasingly associated with personal expression in the face of occasion. This displacement modifies the value proposition: the piece can maintain its symbolic dimension and, at the same time, function as an element of style, individual expression or reward.
The change thus forces us to review some automations in the category. If the consumer buys jewelry during more times of the year, the commercial calendar can gain continuity. If you buy for yourself, the communication can speak directly to whoever chooses and uses the product. And if the motivations multiply, brand building has more territories than romanticism or traditional celebrations.
It also affects the shopping experience. The Jewelers Mutual study indicates that the physical store continues to play a prominent role, usually supported by prior online research. And quality and design appear as the two main decision factors among those who buy jewelry for themselves. This reinforces the importance of working in a coordinated manner on product, brand, digital content and experience at the point of sale.
The culture of self-gifting presents a concrete opportunity for jewelry: to increase its everyday relevance without losing the symbolic value that has historically distinguished the category. The fundamental change is in who determines when it is worth making the purchase. For years, much of jewelry marketing provided answers for occasions that were already established. Now brands have before them a broader scenario that involves understanding what new motivations consumers are incorporating and constructing proposals capable of being relevant also outside the indicated dates.